In the black means having more money coming in than going out. When your income is higher than your expenses, you are in the black. It applies to a person, a business, a government, or a nonprofit.
The in the black meaning is simple. It describes earning more than you spend, if you’re a person, a business, or a government. Think of it as keeping your head above water, with a little left over for the days ahead.
Behind the phrase, though, sits an old bookkeeping habit and a handful of common misunderstandings. Being in the black doesn’t make you rich, and it certainly doesn’t guarantee you’ll stay there.
This guide walks through what the phrase means, where it came from, and how it differs from “in the red.” Along the way, you’ll find practical steps to get in the black and stay there.
What Does “In the Black” Mean?
In the black means having more money coming in than going out. When your income is higher than your expenses, you’re in the black. A business whose revenue beats its costs is in the black too.
The idea fits into one short equation: income minus expenses equals a positive number. Once the result climbs above zero, you’ve made it.
Who Can Be in the Black?
Nobody owns the phrase. It applies to almost any money situation:
- Individuals: Your paycheck covers your bills, with some left over.
- Businesses: Revenue exceeds the cost of running the company, producing a profit.
- Governments: Tax revenue tops spending, creating a budget surplus.
- Nonprofits: Donations and grants cover operating costs with funds to spare.
How People Use the Phrase
“In the black” is an idiom, so it usually travels with verbs like be, stay, get, or return. A few examples show the range:
- “The company is finally in the black after three tough years.”
- “We stayed in the black all year by trimming unnecessary costs.”
- “She took a second job to get back in the black.”
You’ll also see close cousins such as profitable, solvent, surplus, and positive balance. They aren’t perfect synonyms, but they all point in the same healthy direction.
Where Does the Phrase Come From?
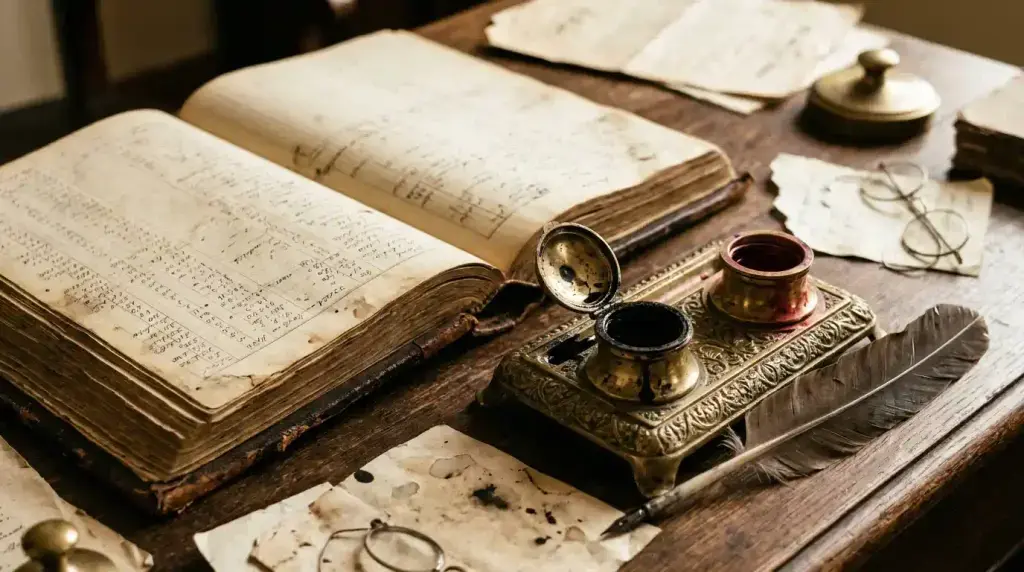
The expression grew out of hand-written bookkeeping. Before accounting software existed, businesses tracked every transaction in paper ledgers, and ink color worked as a quick visual signal. Black ink marked positive balances and profits, while red ink flagged losses and negative balances.
A glance at a page told the story. Black numbers meant a business was doing well; red numbers meant trouble.
From Ledger to Everyday Language
Over time, those colors turned into shorthand. Newspapers, boardrooms, and ordinary conversation borrowed the phrases, and they became familiar in English during the twentieth century. Bookkeeping habits varied from one office to the next, so it’s safest not to claim that every ledger followed the same rule.
Why the Two Phrases Travel Together
“In the black” and “in the red” are almost always taught as a pair. Each one gets its meaning from the contrast with the other, which helps explain why both have stuck around for so long.
Why the Idiom Survived the Digital Age
Paper ledgers are mostly gone, yet the colors live on. Spreadsheets, banking apps, and budgeting tools often show negative numbers in red and positive ones in black or green. Because the visual habit never disappeared, the language still feels natural.
In the Black vs. In the Red
These two phrases sit at opposite ends of the same scale. One says you’re ahead; the other says you’re behind.
| In the Black | In the Red | |
| Meaning | Income exceeds expenses | Expenses exceed income |
| Ledger color | Black ink (positive) | Red ink (negative) |
| Result | Profit or surplus | Loss or deficit |
| Cash position | Money left after bills | Shortfall that must be covered |
| Typical response | Save, invest, or reinvest | Cut costs, borrow, or raise income |
| Credit impact | Generally easier to borrow | Generally harder to borrow |
| Emotional effect | Confidence and breathing room | Stress and pressure |
What Each Position Means in Practice
Being in the black gives you options. A business can hire, expand, or build a cash reserve, while a household can save for goals and absorb surprise expenses without borrowing.
Running in the red isn’t automatically a disaster. Plenty of healthy startups spend more than they earn on purpose while they invest in growth. The danger appears when the shortfall keeps growing with no plan to close it, since that path can lead to mounting debt, damaged credit, or even closure.
The Gray Areas
Real finances rarely split into clean black and red halves.
- Breaking even: Income exactly equals expenses. You’re not losing money, but you’re not building a cushion either.
- Temporary dips: Seasonal slowdowns or a large one-time purchase can push a business into the red for a month before it bounces back.
- Profit versus cash flow: A company can show a profit on paper while running low on actual cash, especially when customers pay slowly.
A useful rule of thumb is to watch the trend rather than a single snapshot. A business that’s slightly in the red but improving every quarter may be healthier than one that’s barely in the black and shrinking.
How the Term Is Used in Different Settings
The meaning never changes, but the way people measure it does.
Personal Finance
For individuals, being in the black means monthly income covers bills, debts, and living costs with something left over. It can also describe a bank account that has moved from overdraft back to a positive balance. People often use the phrase after paying off a credit card or finally sticking to a budget.
Small Business
A first profitable month or quarter is a major milestone for any owner. Startups usually spend heavily on equipment, marketing, and inventory before revenue catches up, so reaching the black signals that the business model works. From that point, owners can pay themselves more consistently or reinvest in growth.
Corporate
In larger companies, the phrase shows up in earnings reports and business headlines, often as “return to the black” after a stretch of losses. Analysts focus on net income and the bottom line, although investors also keep an eye on cash flow and debt.
Government
Governments are in the black when tax revenue and other income exceed spending, which produces a budget surplus. Deficits are more common, so a surplus tends to make the news. Exact figures can be debated depending on what a country or city chooses to count.
Nonprofits
A nonprofit stays in the black when donations, grants, and program income cover operating costs. Unlike a business, it doesn’t pay out the surplus as profit. Instead, the extra funds go back into the mission or into a reserve for leaner years.
Everyday Speech
Outside finance, people use the phrase casually to mean “doing fine” or “back on track.” You might hear someone say, “Between the bonus and the tax refund, I’m back in the black this month.”
Real-World Examples
Definitions help, but stories make the idea stick. The three scenarios below are illustrative rather than real cases.
Example 1: The Freelancer After a Slow Quarter
Imagine a freelance designer whose client work dries up for three months. She dips into savings to cover rent and software subscriptions, which puts her firmly in the red.
To recover, she sends invoices promptly, follows up on late payments, raises her rates for new clients, and cancels two subscriptions she barely uses. Within two months, her income beats her expenses again, and the extra cash rebuilds her savings buffer.
Lesson: When income is irregular, staying in the black means planning for slow months, not just celebrating busy ones.
Example 2: The Restaurant After Launch Costs
A new restaurant owner pours money into kitchen equipment, renovations, licenses, staff training, and marketing before opening day. For the first several months, costs run higher than sales.
As word spreads and regulars return, revenue climbs. Meanwhile, the owner trims food waste and shifts the menu toward high-margin dishes. In month nine, monthly revenue finally overtakes monthly costs.
Lesson: Early losses are normal for many startups. What matters is having enough runway to reach profitability and a clear plan to get there.
Example 3: The Household Escaping Credit Card Debt
A couple has been leaning on credit cards for everyday expenses, and interest charges are eating into their budget. They decide to change course by tracking every expense for 30 days, setting a realistic budget, and attacking the highest-interest card first. Windfalls such as tax refunds go straight toward the debt.
Progress is slow at first. Eventually, their income covers all expenses and debt payments with room to spare, and they start building an emergency fund so they don’t slide back.
Lesson: Small, consistent habits matter more than one dramatic move.
How to Tell If You’re in the Black
Knowing the definition is one thing. Confirming that you are actually in the black takes a little math.
For Personal Finances
Step 1: Calculate monthly cash flow. Add up your after-tax income, then subtract every expense, including rent or mortgage, groceries, debt payments, and subscriptions.
Income – Expenses = Cash Flow
A positive result means you’re in the black for the month. A negative one means you’re in the red.
Step 2: Check the trend. Review the last three to six months, because one strong month can hide a pattern of overspending. Likewise, one rough month, say a car repair, can make a healthy budget look worse than it is.
Step 3: Compare cash flow with net worth. Cash flow shows if you’re earning more than you spend right now. Net worth, which is assets minus debts, shows your overall position. You can be in the black on cash flow and still carry a lot of debt, so track both.
Step 4: Watch for red flags. Even with a positive monthly number, be cautious if you’re covering regular expenses with credit cards, dipping into savings every month, or paying only the minimum on debt.
For Businesses
Owners have a few more tools to work with:
- Profit and loss (P&L) statement: Also called the income statement, it shows revenue minus expenses over a period. A positive net income means the business is profitable.
- Cash flow statement: It tracks actual cash moving in and out. Since profit on paper doesn’t always mean cash in the bank, this statement matters just as much.
- Gross versus net profit: Gross profit is revenue minus the direct cost of producing goods or services. Net profit is what remains after all expenses, including rent, salaries, taxes, and interest.
Key Metrics at a Glance
| Metric | What It Tells You |
| Net income | If the business is profitable overall |
| Operating cash flow | If daily operations generate real cash |
| Burn rate | How fast the business is spending cash |
| Runway | How many months remain before cash runs out |
| Profit margin | What percentage of revenue becomes profit |
A Quick Self-Check
Ask yourself three questions. Did more money come in than went out this month? Has that held true for most of the last six months? Could you cover an unexpected expense without borrowing? If all three answers are yes, you’re not just in the black; you’re on solid ground.
How to Get in the Black
If you’re currently in the red, the goal is to close the gap between what comes in and what goes out. Only two levers exist: spend less and earn more. The steps below pull one or both.
Step 1: Track Every Dollar for 30 Days
You can’t fix what you can’t see. For one month, record every expense, from rent to the morning coffee, using an app, a spreadsheet, or a notebook. Most people are surprised by how much leaks out through small, forgotten purchases.
Step 2: Build a Realistic Budget
Once you know where the money goes, give it a plan. Two popular approaches are worth considering:
- 50/30/20 rule: Roughly 50% of after-tax income goes to needs, 30% to wants, and 20% to savings and debt repayment. People in high-cost areas may need to adjust these percentages.
- Zero-based budgeting: Every dollar gets a job, so income minus planned spending equals zero.
Choose whichever one you’ll actually follow. A simple budget you stick with beats a perfect one you abandon.
Step 3: Cut or Renegotiate Recurring Expenses
Recurring costs are the easiest place to find savings, since one decision keeps paying off every month. Cancel subscriptions you rarely use, compare prices on insurance, phone, and internet plans, and ask providers for better rates. Small habit changes around energy and groceries add up as well.
Step 4: Increase Your Income
Cutting only goes so far, so raising income can speed things up. You might ask for a raise, take on freelance work, sell items you no longer need, or build a skill that boosts your earning power.
Step 5: Pay Down High-Interest Debt
Interest quietly widens the gap between income and expenses. Two common strategies help:
- Avalanche method: Pay off the highest-interest debt first, which saves the most money overall.
- Snowball method: Pay off the smallest balance first, which builds motivation through quick wins.
The math favors the avalanche, but the snowball can keep some people motivated. Whichever you pick, keep making at least the minimum payment on every account.
For Businesses
Companies follow the same logic with a few extra tools. Tighten invoicing by sending bills promptly and setting clear payment terms. Manage inventory based on real demand, since excess stock ties up cash. Review rent, software, and vendor contracts regularly, and revisit pricing, because many businesses undercharge. Finally, focus on your most profitable products and clients, since not all revenue is equally valuable.
Be Patient
Getting in the black rarely happens overnight. Aim for steady progress, such as shrinking your monthly shortfall a little each month, rather than an instant turnaround.
WHAT IS ANNUAL NET INCOME?
Annual net income is the money a person or business keeps after all expenses, taxes, and interest are taken out over one full year.
It is the yearly bottom line, so a positive annual net income means more money came in than went out during that year.
WHAT IS NET INCOME?
Net income is the amount left after all expenses, taxes, and interest are subtracted from total revenue.
For a business it shows whether it made a profit, and for a person it is the money left after bills and taxes are paid.
How to Stay in the Black
Getting there is an achievement; staying there is a habit. Many people and businesses slip back into the red because they stop paying attention once the numbers look good.
Build an Emergency Fund or Cash Reserve
Unexpected costs are the most common reason people fall back. A repair bill, a medical expense, or a sudden drop in income can wipe out a thin margin.
A common guideline for individuals is three to six months of essential expenses in an accessible savings account. If that feels out of reach, start with one month and build gradually. Businesses often aim for several months of operating costs, so a slow season or a late-paying client doesn’t become a crisis.
Review Your Numbers Every Month
Pick a regular date, even if it’s only 20 minutes, to compare planned spending with actual spending. Catching a creeping category early is far easier than fixing a large problem later. Business owners should review the P&L and cash flow statement monthly rather than waiting for tax season.
Automate Savings and Bill Payments
Willpower is unreliable, but automation isn’t. Set up automatic transfers to savings on payday, schedule bill payments to avoid late fees, and use automatic contributions for retirement or investment accounts. When saving happens before you can spend the money, staying in the black takes less effort.
Avoid Lifestyle Creep and Overexpansion
When income rises, expenses love to follow. A raise becomes a nicer apartment, a bigger car payment, and more subscriptions, and the cushion disappears.
Businesses face a similar trap in growing too fast. New hires, locations, and inventory orders can push a profitable company back into the red if revenue doesn’t keep pace. A simple guard for both is to decide in advance how much of any income increase goes to savings.
Plan for Irregular Income
Freelancers, seasonal businesses, and commission-based workers need a different approach. Base your budget on your lowest typical month, save extra during strong months, and pay yourself a steady “salary” from a separate account to smooth out the swings.
Keep an Eye on Warning Signs
Even in the black, watch for early signals of drift: credit cards covering routine expenses, skipped savings contributions, shrinking profit margins, or customers paying later than usual. Spotting these early leaves time to adjust before the numbers turn red.
Common Misconceptions
Because “in the black” sounds like a clear win, people often assume it means more than it does.
“In the Black Means You’re Wealthy”
Not necessarily. The phrase only says income exceeds expenses. Someone with a modest salary who spends slightly less than they earn is in the black, and so is a high earner who saves very little. Wealth depends on assets and net worth.
“In the Black Means You’re Debt-Free”
You can be in the black and still owe money. A household might cover its mortgage and car loan with cash to spare, and a company can be profitable while carrying significant loans.
“A Profitable Business Can’t Run Out of Cash”
This one catches many owners off guard. Profit is an accounting measure, whereas cash pays the bills. Late-paying customers, tied-up inventory, or a large loan payment can drain cash even when the books show a profit.
“Once You’re in the Black, You Stay There”
Financial health isn’t permanent. A job loss, rising costs, or a major client leaving can push anyone back into the red. Treat the black as a position you maintain rather than a finish line you cross.
“Being in the Red Always Means Failure”
Many healthy businesses run in the red on purpose while they invest, and individuals may dip below zero after a one-time expense. What matters is the cause and if a plan exists to recover.
“Breaking Even Is the Same as Being in the Black”
Close, but no. Breaking even leaves no profit and no cushion, while being in the black leaves a surplus. That surplus is what gives you room to save and handle surprises.
Related Idioms and Terms Glossary
Finance language comes with plenty of colorful phrases. These are the ones most closely tied to “in the black.”
Idioms
- In the red: Spending more than you earn, or holding a negative balance.
- Break even: Income equals expenses, with no profit and no loss.
- The bottom line: The final figure on an income statement, or more broadly, the most important point.
- Break the bank: To spend so much that it strains your finances.
- Cash-strapped: Having very little available money.
- Make ends meet: To earn just enough to cover basic expenses.
- Live paycheck to paycheck: To spend nearly everything you earn, leaving little or no savings.
Financial Terms
- Profit: Revenue minus all costs.
- Surplus: An amount beyond what is needed or spent.
- Deficit: The amount by which spending exceeds income.
- Solvent: Able to pay debts as they come due.
- Insolvent: Unable to pay debts as they come due.
- Liquid: Holding enough cash, or assets quickly convertible to cash.
- Net income: Revenue minus all expenses, including taxes and interest.
- Cash flow: The movement of money in and out over a period.
- Burn rate: How quickly a company spends its cash.
- Runway: How long a business can operate at its current burn rate.
- Net worth: Total assets minus total debts.
Many of these terms sound alike but measure different things. Being solvent, for instance, concerns your ability to pay debts, whereas being in the black concerns if income exceeds expenses. You can be one without the other.
Where a Retirement Account Fits In
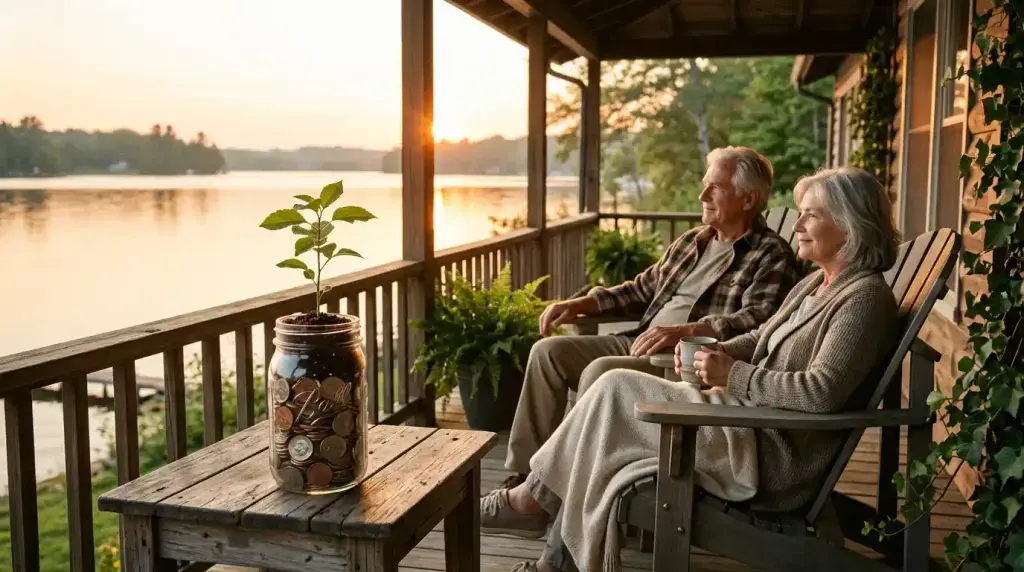
Being in the black is about the present. Long-term financial health also depends on the future, and a person can be in the black every month yet reach retirement with too little saved.
Once your cash flow is positive, the surplus gives you a choice about where it goes. Directing part of it to a retirement account turns a short-term win into a long-term advantage, because money invested early has more years to grow and returns can build on earlier returns. Many retirement accounts also offer tax benefits, though rules differ by account type and country.
What Is an IRA?
An IRA (Individual Retirement Account) is a US retirement savings account that you open on your own, separate from an employer plan. Two common types exist:
- Traditional IRA: Contributions may be tax-deductible, and withdrawals in retirement are generally taxed as income.
- Roth IRA: Contributions use after-tax money, and qualified withdrawals in retirement are generally tax-free.
Readers outside the United States will have their own equivalents, such as workplace pensions or tax-advantaged savings accounts.
Where It Fits in Your Priorities
A common sequence looks like this:
- Get in the black by making income exceed expenses.
- Build a starter emergency fund.
- Pay down high-interest debt.
- Contribute to retirement accounts, especially if an employer offers a match.
- Keep growing savings and investments over time.
Your situation may call for a different order. You don’t need a large amount to begin, either, since a small automatic contribution each payday builds the habit, and you can raise it as your income grows.
This article provides general information only and is not personalized financial, tax, or investment advice. Rules, limits, and eligibility for retirement accounts change over time, so consider speaking with a qualified professional before making decisions.
FAQS
What does “in the black” mean in simple terms?
It means you’re earning more than you’re spending. The phrase applies to individuals, businesses, governments, and nonprofits alike.
Is “in the black” good?
Generally, yes. It shows you’re covering your costs and have a surplus to save or invest. Still, you can be in the black while carrying debt or holding little savings, so look at your overall financial health too.
What is the opposite of “in the black”?
The opposite is “in the red,” which means expenses exceed income or an account has a negative balance.
Why is it called “in the black”?
Traditional bookkeeping used black ink for positive balances and profits, and red ink for losses. Black numbers in a ledger signaled financial health, and the color became everyday shorthand.
Can a company be in the black and still have cash problems?
Yes. Profit is an accounting measure, but cash pays the bills. Slow-paying customers, tied-up inventory, or a large loan payment can create a cash shortage even when the books show a profit.
Is breaking even the same as being in the black?
No. Breaking even means income equals expenses, so there’s no cushion. Being in the black means a surplus remains.
How do I know if I’m in the black?
Subtract your monthly expenses from your after-tax income. A positive result means you’re in the black, and checking several months in a row gives the most reliable picture.
How can I get back in the black?
Track spending, build a realistic budget, cut recurring costs, raise your income, and pay down high-interest debt. Businesses can also tighten invoicing, manage inventory, and review pricing.
Does being in the black mean I’m debt-free?
No. It means your income covers your obligations, including debt payments, not that you have no debt.
What does in the black mean in simple terms?
It means you’re earning more than you’re spending. The phrase applies to individuals, businesses, governments, and nonprofits.
How can I get back in the black?
Track spending, build a realistic budget, cut recurring costs, raise your income, and pay down high-interest debt. Businesses can also tighten invoicing, manage inventory, and review pricing.
Conclusion:
The idea behind “in the black” is simple and old: more money coming in than going out. What began as a bookkeeping convention, black ink for gains and red for losses, has grown into one of the most recognizable phrases in personal finance, business, and government.
Key Takeaways
- In the black means income exceeds expenses, while in the red means the reverse.
- The phrase applies to individuals, businesses, governments, and nonprofits.
- Being in the black doesn’t mean you’re wealthy or debt-free, and a profitable business can still run short of cash.
- To get there, track spending, budget realistically, cut recurring costs, raise income, and tackle high-interest debt.
- To stay there, build a reserve, review your numbers monthly, automate savings, and watch for warning signs.
Hi, I’m Rida, the writer behind this site about word meanings.
I explain words in simple English with clear definitions, synonyms, and real examples.
My goal is to help learners and curious readers pick the right word with confidence.
Every article is checked against trusted dictionaries so you can learn with trust.